Ask a mortgage shop owner how business is going and you'll often hear some version of “We're the biggest in town.” Maybe it's the purchase business in your home county, or the go-to name with a handful of builders. It feels like winning. It can also be a ceiling you haven't noticed yet.
Market share is a ratio, and a ratio says nothing about how big the thing is that you're dividing. Fifty percent of a small market is still small. Five percent of a big one can change your company.
What does the math actually say?
Here's a made-up example. Shop A holds half of a county that produces $500 million a year. Shop B holds 5% of a metro that produces $10 billion. Shop A is the local legend with $250 million. Shop B is barely a blip and has $500 million.
Now zoom out. MBA's September forecast puts total 2026 originations at about $2.123 trillion. The national market is large enough that most shops will never run out of room. Plenty of shops run out of room in their own backyard.
If you can't grow without taking loans from the same three competitors, you've outgrown your market.
Why do shops get stuck in the small pond?
Because it's flattering and easy to measure. You know every competitor by name. You know who's slipping and who's hiring. Being number one locally feels like proof the strategy works.
But once you own most of a small market, the only way to grow is to pull loans from the few competitors left, and that usually means richer comp and sharper pricing. You're also tied to one local economy. If a big employer cuts back or a few of your top producers leave, there's nowhere else for your volume to come from.
Where should a shop look instead?
Look for the counties where total production is large and your share is small. That's where a few good hires can move the needle without starting a fight.
It's also a market in motion. Over 27,000 producing loan officers changed employers in the last 10 months. Producers who are already open to a conversation are sitting in the markets you haven't touched.
How does a shop go after a bigger slice?
Pick the county before the person. Rank counties by total production, then compare your volume in each. The thin spots in big counties are your targets.
Recruit into the market you want. A producer who already works a county has the agents, builders and referral partners. You're hiring relationships, not just a license.
Watch tenure. Loan officers tend to move around the two-year mark. Knowing who's approaching it helps you time the conversation.
Verify before you offer. Look at production, product mix and employment history first, so you know what you're actually getting.
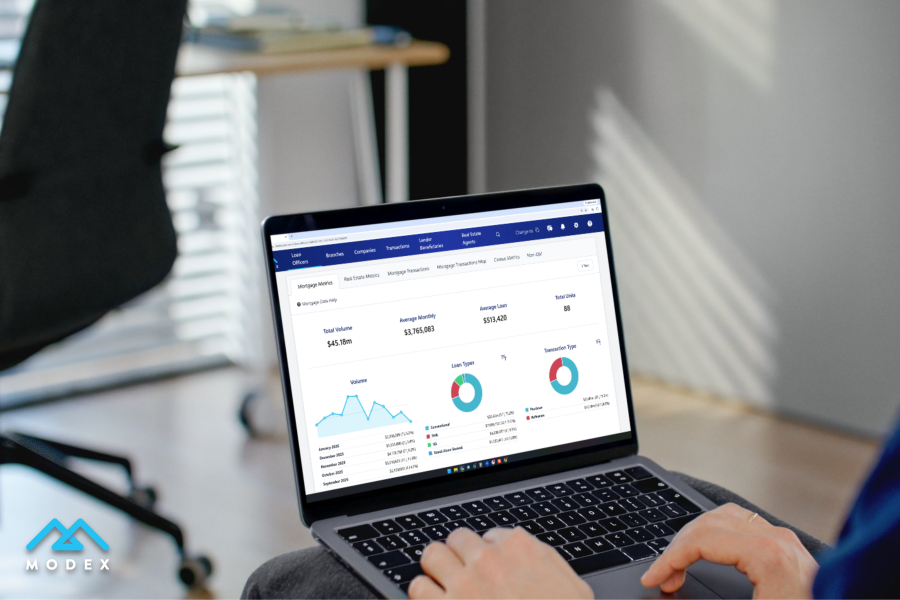
This is where county-level data helps. Modex pulls from deeds of trust in 2,370 counties, covering 95% of the U.S. population's residential home loans, so you can see where the volume is, who's producing it, and which companies are already there.
None of this means walking away from your home market. It's your base, and your reputation there is worth a lot. The mistake is thinking it's your whole opportunity.
The takeaway
Next time you're proud of a market share number, ask what it's a share of. Being the biggest in a small market is nice. Being a real player in a large one is how a shop keeps growing.
Want to see where your shop's share is thinnest? Log in to Modex and rank the counties you're licensed in by total production.