Every recruiting leader wants the same thing: someone who ramps fast, stays, and becomes a top producer. But that person rarely has a track record yet. No book of business, no LinkedIn history worth searching, maybe just a title change from six months ago. So most recruiters pass on them and go fight over the same small pool of veteran producers everyone else is already chasing. Meanwhile, the next great originator gets hired by whoever actually noticed them first.
Why Is Rookie Recruiting Such a Gamble?
By some estimates, roughly half of new loan officers don't make it past their first year. And hiring one isn't free: the average cost to bring on a new loan officer runs north of $4,400, and new hires typically need up to 12 weeks before they're producing at full capacity.
That combination of a high failure rate, a real cost, and a long runway before you know whether it worked is exactly why most recruiters avoid rookies and chase experienced producers instead. But experienced producers come with their own headaches: bidding wars, non-competes, and a price tag that keeps climbing as the pool of available veteran loan officers keeps shrinking.
What Does Real Rookie of the Year Potential Look Like?
Some mortgage companies already track this internally. What is missing for most recruiters is visibility into who that person is at a competitor, in a different market, or brand new to the industry altogether.
The signal that actually matters isn't potential on paper. It's early production. A newly licensed loan officer who closes three or four loans in their first quarter, while most of their peer group closes zero, is telling you something a resume never could. That kind of early traction usually points to strong training, a referral network already forming, or someone who simply outworks the average rookie. Whatever the reason, it's about as close to a guarantee as rookie hiring gets.
They're producing before they're supposed to. Most new loan officers need months to close a first deal. Someone closing volume in their first 60 to 90 days is outpacing the curve.
They're diversifying fast. A rookie who has already touched more than one loan type or referral source is building habits, not riding a single lucky deal.
They're at a shop with a track record of developing talent. Production tells you about the person. Where they're producing tells you about the training and mentorship behind them.
How Can You Find These People Before Anyone Else Does?
This is where most recruiting tools fall short. Job boards and LinkedIn show you who's looking, not who's winning. Traditional prospecting surfaces experienced producers because that's who shows up in the usual searches. Nobody is publishing a list of loan officers who got licensed eight months ago and are already producing.
Modex closes that gap by combining two data sources that, together, do something neither can do alone.
Monthly NMLS refreshes flag who's new. Modex updates NMLS data every month, capturing new licenses, company moves, and branch changes as they happen. This is how you know someone got licensed six, nine, or twelve months ago.
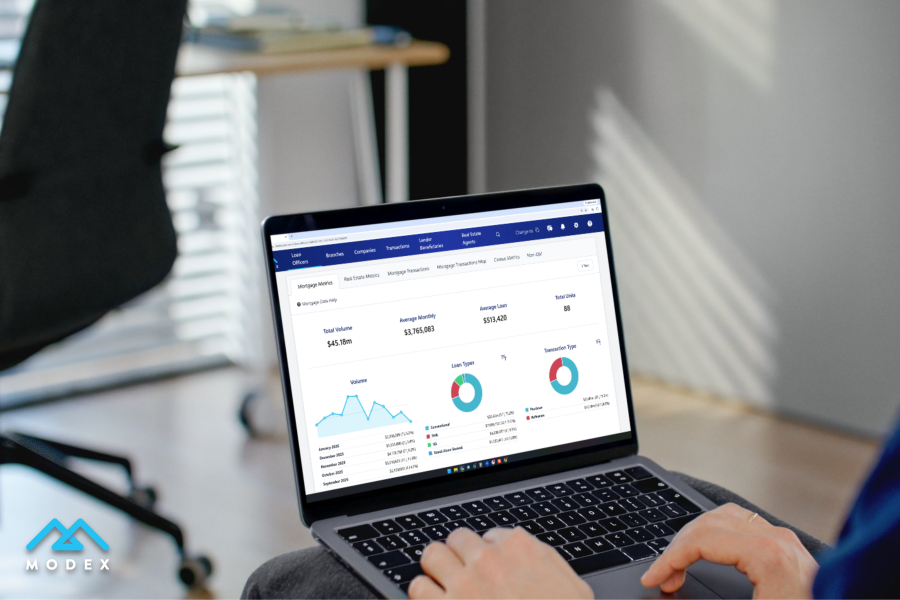
County-level deed of trust data shows who's actually closing. Sourced from public record filings across 2,370 counties, covering 95 percent of U.S. residential home loans, Modex production data reflects real, closed transactions at the individual loan officer level, not self-reported numbers.
Cross-reference the two and you get something no resume, referral, or cold call can offer: a filtered list of loan officers licensed within the past year who are already producing above their peer group, sorted by county, company, or product mix.
What's the Fastest Way to Find Non-QM Opportunities Before Your Competitors Do?
Most loan officers understand the theory behind non-QM. Far fewer know where the deals are happening or which loan officers and branches are already building a book in it. That's where most originators lose the race: non-QM prospecting has traditionally relied on referrals and cold outreach, an approach that works, but slowly and unevenly across a market this large.
What Should a Rookie-Sourcing Workflow Look Like?
A few practical filters make this repeatable rather than a one-time search:
Filter by years in industry. Start with loan officers licensed in the trailing 6 to 12 months so you're looking at true rookies, not seasoned producers who recently moved.
Layer in production thresholds. Add a minimum unit or volume filter to separate early producers from loan officers who are licensed but still inactive.
Watch specific branches and companies. If one branch keeps turning out strong rookies year after year, that branch's training culture is worth watching, and its rookies are worth calling before they get comfortable.
Track monthly, not once. New licensees show up in the data every month. A one-time search misses everyone who gets licensed next quarter.
Export and reach out with specifics. Once the list is built, Modex's contact data and CRM sync let you move from list to outreach without a manual data hunt in between.
The Bottom Line
The best rookie hire of the year is out there right now, closing loans somewhere without a headline, an award, or a LinkedIn post to show for it yet. By the time they win an actual Rookie of the Year title or land on a Rising Stars list, every recruiter in the market already knows their name, and the price to hire them has gone up accordingly.
The recruiters who win this game aren't the ones with the best pitch. They're the ones who found the right person first, based on what the data already showed, months before anyone else thought to look.